
tax savings evaluation
A tax savings evaluation examines how your business structure, income, assets, and plans may affect your tax position. It can identify strategies to analyze before a transaction or filing deadline, along with limits, costs, or documentation requirements that may make an idea unsuitable.
Key Takeaways
- A tax savings evaluation reviews your business structure, income, assets, and future plans to reveal strategies worth analyzing ahead of major transactions or filing deadlines.
- Not every promising idea survives scrutiny, since limits, costs, or documentation requirements can disqualify a strategy that initially looked attractive.
- Evaluating your tax position before a transaction gives you time to compare options rather than react under deadline pressure.
- Understanding what could make a strategy unsuitable helps business owners set realistic expectations about potential savings.
- Working through this evaluation systematically supports better decisions about which tax strategies fit your specific circumstances.
Trucess Tax Advisory’s Tax Savings Evaluation is a structured planning engagement, distinct from preparing a return. It starts with your facts, not a promise of a deduction or tax result.
What a Tax Savings Evaluation Is (and How It Differs From Tax Preparation)
A tax savings evaluation reviews a taxpayer’s financial and tax circumstances to identify and assess possible planning strategies. It considers whether a strategy fits the facts, whether its tax effect may be usable, and what implementation steps and records are required. It does not replace return preparation, guarantee savings, or establish eligibility by itself.
Definition: A Structured Review of Your Tax Position, Not a One-Off Trick
The review may cover business and individual returns, entity structure, income sources, property ownership and basis, depreciation history, planned purchases or sales, and the owner’s goals. For a property owner, that can include how an asset is used and whether its tax treatment aligns with its function. A ranch’s fences, wells, livestock structures, and general-purpose buildings may have different depreciation classifications. Each asset needs fact-specific analysis; its location on a farm does not by itself establish a shorter recovery period.
Tax Savings Evaluation vs. Tax Return Preparation: Timing, Scope, and Purpose
Return preparation reports financial activity and tax positions for a completed year, based on records and filing requirements. An evaluation addresses planning questions: which options merit review, what assumptions apply, and what decisions or records may be needed. It can inform future action, but implementation and return preparation are separate work. Trucess Tax Advisory offers return preparation when separately engaged.
| Consideration | Tax planning evaluation | Tax return preparation |
|---|---|---|
| Primary purpose | Assess potential strategies and their fit | Prepare a return from year-specific records |
| Typical timing | Before or during decisions, and as circumstances change | After or near the close of the tax year, subject to filing deadlines |
| Key output | Analysis of assumptions, constraints, and possible next steps | Completed return, if separately engaged |
Who Should Consider a Tax Savings Evaluation
Property owners may consider one before acquiring, constructing, improving, selling, or changing the use of business or rental property. Revenue alone does not determine suitability; objectives, records, tax profile, and whether a strategy justifies its costs and work also matter.
The Evaluation Framework: How to Assess Tax Savings Opportunities Step by Step
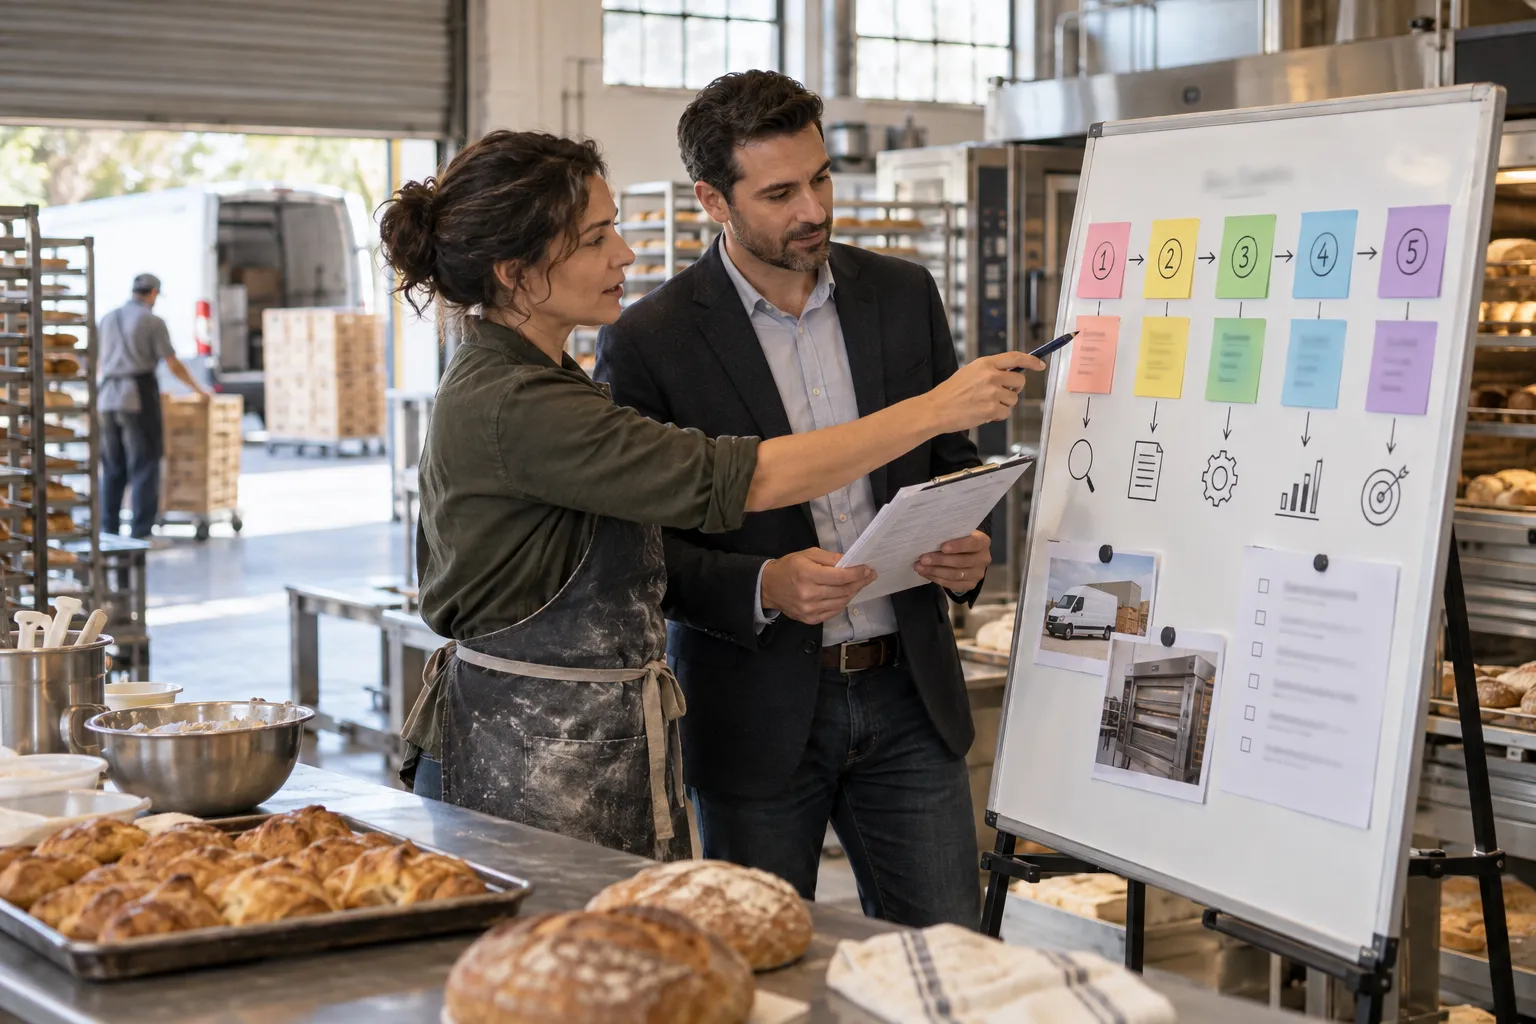
A useful evaluation establishes facts, screens possible approaches, tests whether tax benefits can be used, estimates consequences, and documents and monitors approved action. This keeps a familiar strategy from being treated as automatically suitable. It also distinguishes a projected deduction from a projected tax reduction, which depends on the taxpayer’s circumstances and current law.
Step 1: Gather Facts: Entity Structure, Returns, Property Basis, and Goals
Start with recent federal returns, financial statements, entity documents, ownership records, fixed-asset schedules, invoices, closing statements, and depreciation history. Add property use, placed-in-service dates, financing, planned transactions, and changes in business activity. For real estate, basis and cost records frame depreciation analysis; asset function matters as much as the label “farm” or “rental.” Include goals such as funding equipment purchases, managing taxable income across years, or planning a transition. Treat missing records as an open issue, not an invitation to assume facts.
Step 2: Screen Candidate Strategies Against Your Facts
Compare candidate approaches with the facts and applicable rules. Screening may cover cost segregation, Section 179, bonus depreciation under Section 168(k), the qualified business income deduction, entity-structure tax analysis, retirement plan contributions, and income or expense timing. Check eligibility, acquisition and placed-in-service dates, business use, ownership, and other requirements before estimating effects. Depreciation classification depends on an asset’s function and tax rules, not merely its setting. Remove strategies that do not fit before implementation costs accumulate.
Step 3: Test Usability: Passive Activity, Material Participation, and Deduction Capacity
A deduction’s timing and practical value depend on whether the taxpayer can use it. Review passive activity limits under IRC Section 469, participation in the relevant activity, income characteristics, and other applicable deduction limits. A loss from one activity may not offset another activity’s income as expected. Consider ownership and operational facts, including who performs work and how the activity is classified. If usability is uncertain, identify the issue for professional analysis rather than presenting a projected deduction as an immediate benefit.
Step 4: Quantify Projected Effects and Weigh Costs, Recapture, and Tradeoffs
Model potential outcomes using stated assumptions, including tax year, income, asset use, filing status, and applicable limits. Compare deduction timing with professional and implementation costs, cash-flow needs, and later-year effects. Accelerated depreciation generally changes when deductions occur, not necessarily their total over an asset’s life. A disposition or change in use may affect prior tax treatment. Show uncertainty, distinguish a modeled outcome from a promised saving, and revise projections when assumptions change.
Step 5: Document, Implement, and Monitor on an Ongoing Basis
Before acting, assign responsibility for each filing, election, study, accounting adjustment, and recordkeeping task. Keep invoices, contracts, placed-in-service evidence, business-use records, and written analysis with the tax file. Review depreciation schedules annually and when significant assets are acquired, built, sold, converted to personal use, leased, or otherwise changed in use. Monitoring can reveal when an assumption no longer reflects operations. The sequence is facts and records, strategy screening, usability review, projections, documented implementation, and follow-up.
- Gather returns, entity records, asset details, and goals.
- Screen only strategies that fit documented facts.
- Check limits, participation, deduction capacity, costs, and future consequences.
- Assign implementation and recordkeeping responsibilities, then revisit material changes.
Key Strategies to Evaluate: Eligibility, Fit, and Limitations
Assess potential strategies against ownership, business use, income, timing, and records. A deduction available under one set of facts may be unusable or uneconomical under another. The Tax Savings Evaluation can assess which approaches warrant further review, including assumptions, implementation requirements, and projected effects. Verify current-law details, elections, and thresholds before decisions or filings.
Depreciation and Cost Segregation: Accelerating Deduction Timing on Business and Rental Property
Depreciation depends on an asset’s function, use, cost, and placed-in-service date. Cost segregation may identify building components with different recovery periods and accelerate deductions; it does not guarantee permanent tax savings. The IRS Cost Segregation Audit Technique Guide, Publication 5653, describes examination considerations, not a safe harbor or approval of a particular study.
Classification matters on farms and ranches. IRS Publication 225 lists agricultural fences as 7-year property under GDS and 10-year property under ADS. Farming water wells generally have 15-year GDS and 20-year ADS treatment; drainage generally has a 15-year GDS recovery period. Pumps, piping, tanks, and electrical components may require separate analysis. Earthen ponds, stock tanks, terraces, and land shaping are not manufactured systems: costs without a determinable useful life may be nondepreciable, while qualifying conservation expenditures may warrant review under Section 175. Section 168(i)(13) provides 10-year treatment for qualifying single-purpose livestock structures, subject to a strict design, construction, and exclusive-use test involving housing, raising, and feeding a particular livestock type and its produce, plus necessary equipment housing. General-purpose farm buildings generally use 20-year property treatment. A tax preparer must confirm the statutory wording and its application before publication or implementation.
Section 179 vs. Bonus Depreciation: Comparison for Business Property Owners
Both provisions may accelerate deductions for qualifying business property, with different eligibility rules, limits, and election considerations. The 2026 Section 179 limit is $2,560,000, reduced when qualifying property exceeds $4,090,000 and fully phased out at $6,650,000. Confirm these amounts against current primary authority before acting.
| Factor | Section 179 | Bonus depreciation |
|---|---|---|
| Deduction approach | Taxpayer elects to expense eligible property, subject to statutory limits | Applies under Section 168(k) to qualifying property, subject to applicable rules |
| Limits to review | Annual dollar cap and investment phaseout; taxable business income limits may apply | Acquisition date, property class, business use, and other qualification rules |
| Planning question | Would an election fit projected income and future-year needs? | Would accelerated deductions be usable and beneficial in the relevant year? |
Qualified Business Income (QBI) Deduction and Entity Structure Analysis
The QBI deduction under Section 199A may be available to eligible owners of certain pass-through businesses, subject to taxable-income thresholds, business type, wages, property, and other statutory rules. Entity analysis should consider effects on income reporting, payroll, ownership, and compliance costs, not just one deduction. A change may create administrative or tax consequences greater than its projected benefit. Model the owner’s circumstances and confirm eligibility under the relevant year’s rules.
Retirement Plan Contributions and Income/Deduction Timing
Employer retirement plans may create deductible contributions and support employee benefits, but plan type, eligibility, contribution limits, deadlines, and administration affect the result. Evaluate cash flow, compensation, workforce characteristics, and contribution timing alongside projected income. Tax treatment is one part of the decision; Trucess Tax Advisory provides tax planning, not investment management or broad retirement-income planning. Plan design and administration may require qualified providers.
Strategies That May Not Fit: Common Limitations and Red Flags
A strategy may be unsuitable when records are incomplete, business use is limited, costs exceed projected tax effects, or the taxpayer cannot use a deduction now. Passive activity limits under IRC Section 469 may restrict losses, depending on participation and other facts. Personal-use property, uncertain classifications, late documentation, and unsupported business purposes merit caution. Another owner’s use of an idea does not make it appropriate for you.
Potential fit: Records support ownership, cost, dates, and business use, and the projected treatment addresses a defined goal. Reasons to pause: Eligibility is unresolved, assumptions cannot be substantiated, or recapture and future-year effects have not been modeled. Trucess Tax Advisory’s Tax Savings Evaluation can help determine whether further analysis is warranted; it does not establish eligibility or promise a result.
Illustrative Case Study: A Tax Savings Evaluation for a Hypothetical Texas Property Owner
Illustrative hypothetical only: The facts and possible outcomes below are fictional, not typical results. Actual tax treatment depends on records, operations, applicable law, and professional review.
The Scenario and Stated Assumptions
Suppose a Texas owner operates a cattle ranch through a business entity and owns a residential rental property. During the year, the owner purchases ranch equipment, replaces fencing, and completes water-system work. The rental property has a depreciation schedule, but the owner is unsure whether prior improvements were recorded accurately. Assume invoices and closing documents are available, while participation, asset use, placed-in-service dates, and tax basis need confirmation. These limited facts do not support a responsible projected tax result.
Applying the Evaluation Framework: Screening, Usability Testing, and Projection
The review would separate assets by function and use. Equipment, fencing, wells, and rental improvements need appropriate classification; the ranch setting alone does not determine recovery periods. Records would be checked against work completed, ownership, business use, and dates. The analysis would then screen applicable depreciation rules and whether a proposed study or accounting adjustment is economically justified.
Before estimating an effect, the reviewer would test whether deductions could be used that year by examining income, participation, entity reporting, and potential limits, including passive activity rules under IRC Section 469 where applicable. A projection would state assumptions and account for professional costs, cash-flow needs, and future consequences. Unclear records or participation facts should leave the result unresolved, not be presented as a dependable benefit.
What the Evaluation Would and Would Not Conclude
The analysis could identify documentation questions, candidate treatments for professional review, and implementation tasks if a position is supported. It would not establish that every ranch asset qualifies for accelerated deductions, guarantee a tax reduction, or replace return preparation. Proceed only when records, eligibility analysis, projected economics, and filing steps support the decision. Trucess Tax Advisory’s Tax Savings Evaluation provides a structured assessment, with conclusions limited to the engagement’s facts and scope.
Myths, Timing, and Next Steps: Getting an Evaluation Done Right
Myth vs. Fact: Evaluations Are Not Only for the Wealthy, and Legitimate Planning Is Not ‘Aggressive’
Myth: Tax planning is useful only for very high-income owners, or proactive strategies are inherently aggressive. Fact: The value of a review depends on circumstances, records, decisions, and planning questions, not wealth alone. Responsible planning applies rules to documented facts, considers limitations, and explains uncertainty. Proposals based on unsupported business purpose, incomplete records, or promised results deserve scrutiny, regardless of who presents them.
How Often Should Business Owners Revisit Their Tax Plan?
Review planning at least annually and after significant changes, such as property acquisitions or sales, improvements, changed business use, ownership restructuring, or substantial income shifts. Revisit depreciation records when significant assets are acquired, built, sold, converted to personal use, leased, or changed in use. Timing also depends on transaction deadlines and time needed to gather records. Periodic reviews do not replace timely return preparation or separately arranged quarterly advisory work.
Checklist: Is a Strategy Right for Your Facts?
Use this checklist to identify gaps before implementation. A “no” or “not sure” calls for investigation, not automatic rejection.
- Can you document ownership, cost, dates, and business or rental use?
- Do the stated eligibility rules match your entity, activity, and property facts?
- Have deduction limits, participation, and the ability to use the tax benefit been assessed?
- Does the projection disclose assumptions, costs, and possible effects in later years?
- Are filing responsibilities, elections, and recordkeeping steps clearly assigned?
When to Involve a Professional, and How a Tax Savings Evaluation Differs From a Discovery Call
Seek professional input for property classification, entity changes, substantial transactions, uncertain deduction usability, or records that may not support proposed treatment. Trucess Tax Advisory’s complimentary 30-minute Discovery Call is an initial conversation about your circumstances and possible fit. It differs from the Tax Savings Evaluation, a planning engagement, and from a written Initial Tax Plan. The evaluation and plan are separate steps; confirm scope and applicable engagement terms before work begins. Neither discussion promises a specific tax outcome.
Frequently Asked Questions
Why can't a projected deduction be treated as a guaranteed tax reduction?
A deduction’s practical value depends on whether the taxpayer can actually use it, which involves passive activity limits under IRC Section 469, material participation, income characteristics, and other deduction limits. Accelerated depreciation also changes deduction timing rather than necessarily producing a permanent reduction in total tax.